NADDC Moves to License Nigeria’s Motor Dealers as Portal Targets Fraud, Finance Gaps

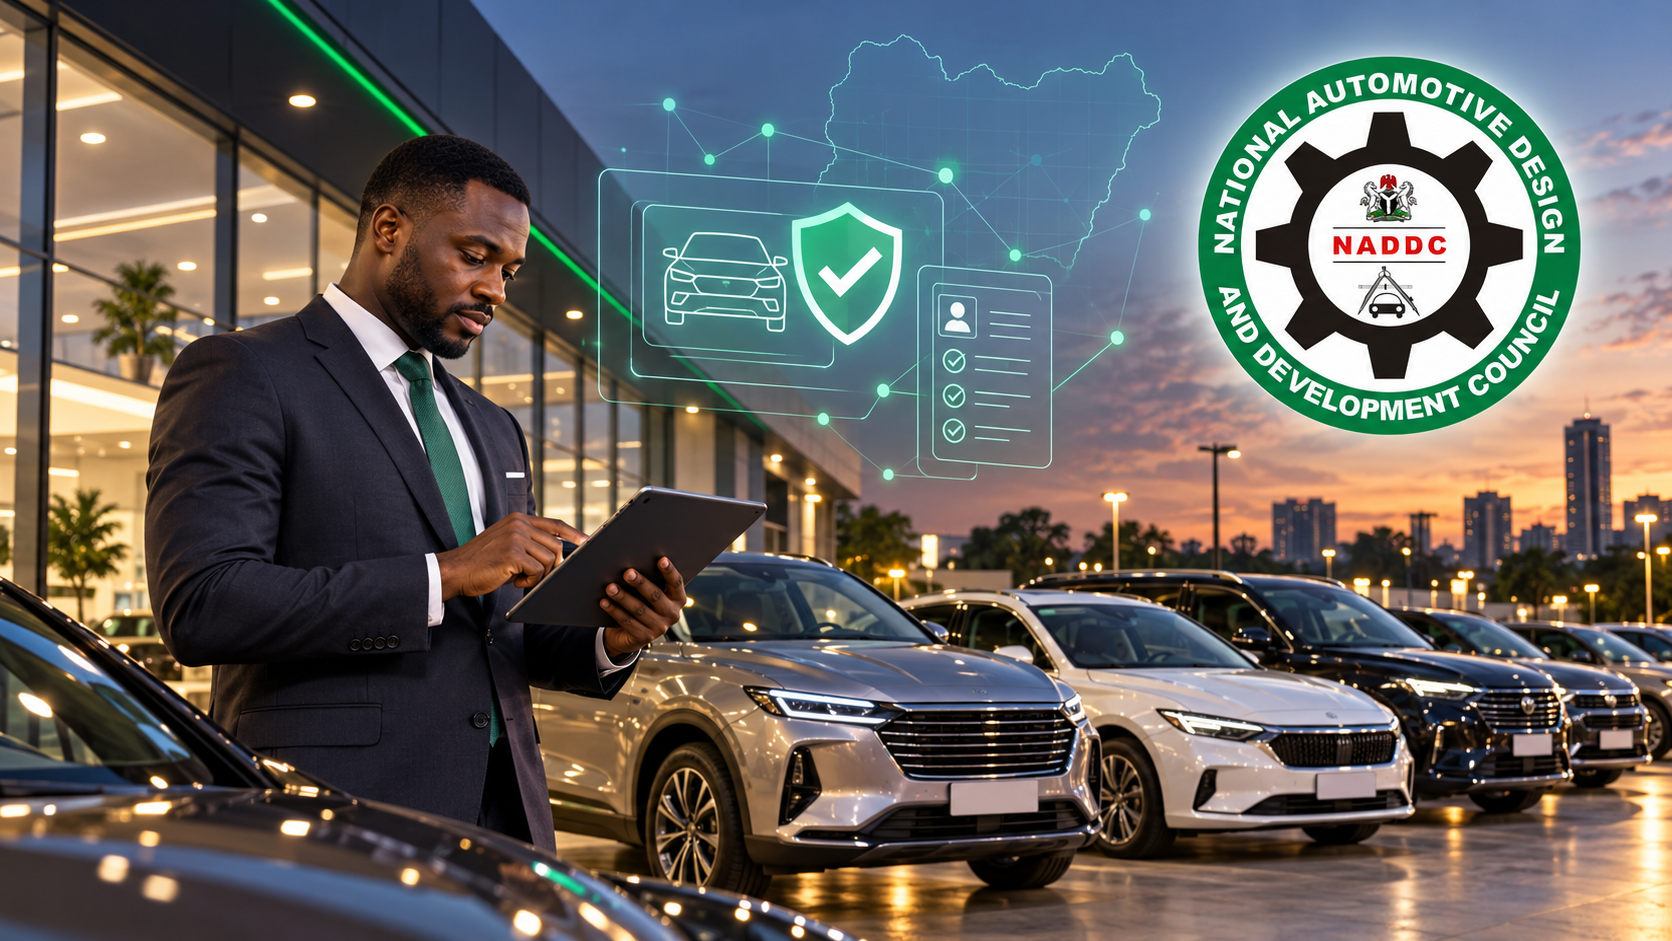 Nigeria’s sprawling motor-dealership market is entering a new regulatory era as the National Automotive Design and Development Council (NADDC) moves to register and license operators through a central digital platform.
The initiative promises to give legitimate dealers formal identities, improve consumer protection, strengthen vehicle traceability and unlock financing. Its success, however, will depend on whether implementation delivers genuine commercial value without creating another layer of fees and bureaucracy.
NADDC Director-General Joseph Osanipin outlined the programme at a sensitisation workshop for members of the Association of Motor Dealers of Nigeria in Abuja.
Osanipin said the online portal should not be interpreted as a new tax mechanism or administrative barrier. Instead, he presented it as a formalisation framework intended to protect verified local investors, improve market data and give credible dealerships recognisable identities within Nigeria’s digital economy.
That distinction matters. Vehicle retailing in Nigeria is a multibillion-naira industry, but much of it remains fragmented, cash-driven and weakly documented. Formal dealerships, independent importers, roadside operators, online vendors and informal intermediaries compete within the same market, often without common standards for ownership verification, warranty disclosure or after-sales responsibility.
Formalising a fragmented market
According to Osanipin, the absence of reliable dealership data has made it difficult for the government to understand market dynamics, enforce standards or curb grey-market imports.
Consumers face even greater exposure. Buyers can unknowingly acquire improperly imported, structurally defective or inaccurately described vehicles, frequently with limited avenues for redress. Where a seller has no traceable business identity, recovering money or enforcing a warranty becomes difficult.
The portal is intended to create a unified register of legitimate motor dealers and distinguish accredited businesses from fraudulent or unverified operators. NADDC expects the system to connect dealership information with relevant government and commercial databases.
Osanipin said integration with the Nigeria Customs Service and tax authorities would help identify uncustomed vehicles, reduce smuggling and address overlapping tax demands.
Yet digital integration cannot eliminate multiple taxation on its own. That will require legal harmonisation, cooperation among federal, state and local authorities, and clarity on which agency is authorised to impose each charge. Without this coordination, dealers could obtain federal accreditation and still face duplicated levies elsewhere.
Auto finance may be the bigger prize
Beyond enforcement, the strongest economic argument for the registry is its potential to close Nigeria’s automotive financing gap.
Commercial banks and other lenders often struggle to finance dealerships because they cannot reliably verify operators, inventory, transaction histories or beneficial ownership. This uncertainty raises the cost of credit and limits the availability of dealership inventory finance, vehicle loans and leasing products.
NADDC believes a verified registry can bridge the information gap among dealers, banks, original equipment manufacturers and authorised distributors. If properly structured, the platform could support inventory financing, asset-backed lending, insurance integration and more credible consumer-credit assessment.
For legitimate dealers, formalisation could become more than regulatory compliance. It could provide an economic identity capable of generating a verifiable trading history and improving access to finance.
Banks would still need to conduct independent credit assessments. Registration alone does not make a dealership solvent or its inventory acceptable as collateral. Nevertheless, dependable data could reduce verification costs and make risk-based lending more practical.
The reform could also support Nigeria’s emerging consumer-credit market. A trusted dealership network would give lenders clearer counterparties, while buyers could gain access to structured repayment products instead of relying almost entirely on cash purchases.
Government procurement meets the Nigeria First agenda
Osanipin said accredited local vehicle assemblers and their authorised dealership networks would receive priority consideration in government fleet purchases under the Nigeria First Policy.
This could create a dependable demand channel for domestic manufacturers, assemblers and component suppliers. Government remains one of Nigeria’s largest purchasers of vehicles, and directing more procurement towards locally assembled products could support production volumes, jobs and supplier development.
However, accreditation must not become a shortcut around competitive procurement. Public fleet contracts should remain transparent, price-sensitive and subject to published technical standards. A closed register that favours politically connected businesses would merely replace informality with regulatory privilege.
The register should consequently be searchable, its admission requirements publicly available, and decisions open to review. Dealers denied accreditation should have access to a clear appeal process.
NADDC also expects registered dealers to benefit from expanding trade opportunities under the African Continental Free Trade Area. A recognised commercial identity could help credible operators establish relationships with manufacturers, distributors and logistics partners across Africa.
Cross-border opportunity will nevertheless depend on rules of origin, harmonised vehicle standards, customs efficiency and the ability to distinguish genuinely African automotive production from simple trans-shipment.
EFCC sees value in traceable transactions
The Economic and Financial Crimes Commission has welcomed the registration programme.
EFCC Director of Operations Abdulkarim Chukkah said properly documented dealership and transaction records could help investigators identify individuals and trace financial flows during investigations. He indicated that the commission was prepared to work with NADDC to strengthen procedures and combat economic and financial crimes.
Vehicle transactions can be attractive channels for concealing illicit funds because high-value assets may be purchased, transferred or resold through poorly documented arrangements. A properly governed registry could improve traceability and reinforce anti-money-laundering compliance.
That enforcement value must be balanced with data protection. The portal will hold commercially sensitive and potentially personal information, making cybersecurity, access controls and clear data-sharing rules essential. Dealers and customers need to know which agencies can access their information, for what purpose and under what legal authority.
Dealers back the licensing drive
AMDON President Prince Ajibola Adedoyin said the registration exercise would help remove unregistered operators from the formal motor market. He suggested that enforcement could begin within months, possibly before the end of the year.
That timeframe should be treated as an industry expectation until NADDC publishes a definitive implementation calendar, transition arrangements and enforcement rules.
AMDON National Secretary Alhaji Ibrahim Kaso said relations between the association and NADDC had improved from mutual suspicion to cooperation. He pledged the association’s support for implementation across the 36 states and the Federal Capital Territory.
Industry cooperation will be crucial. Dealers need sufficient time to understand registration requirements, correct documentation gaps and adapt their systems. Abrupt enforcement could push smaller operators further underground or concentrate the market in the hands of larger businesses.
A proportionate framework should differentiate between genuine compliance failures, administrative mistakes and deliberate criminal conduct.
Market implications
A credible dealer registry could gradually reorganise competition around traceability, service quality and financial capacity rather than access to informal supply channels.
Formal dealerships may gain an advantage through finance, procurement eligibility and stronger manufacturer relationships. Banks, insurers, leasing companies, automotive fintechs and vehicle-history platforms could also build products around verified dealer data.
Consolidation is likely if registration costs, capital requirements or technology obligations prove too demanding for smaller dealers. That may improve professionalism but could reduce competition unless independent operators receive realistic compliance support.
The final market effect will therefore depend on cost. NADDC’s assurance that the platform is not a tax scheme must be reflected in transparent fees, predictable renewal requirements and measurable benefits.
Brand implications
For motor dealers, accreditation could become a valuable trust signal. A visible verification mark may reassure customers that a business is traceable and accountable.
But registration alone cannot guarantee vehicle quality. Consumer trust will require enforceable disclosure standards, verified customs status, mileage and accident-history transparency, warranty obligations and an accessible complaints system.
For NADDC, the portal is also a test of institutional reputation. If registration is fast, transparent and commercially useful, the council can position itself as an industry enabler. If the process becomes slow, expensive or vulnerable to favouritism, “formalisation” will be interpreted as another revenue-collection exercise.
Investor relevance
Reliable sector data would improve the ability of investors to estimate market size, dealership density, vehicle demand and regional distribution. It could also help OEMs select credible partners and allow lenders to design products around documented inventory and cash flow.
The strongest opportunities may emerge in dealer financing, vehicle leasing, insurance, inspection technology, digital marketplaces, aftermarket services and verified used-car platforms.
Investors should nevertheless watch the final licensing conditions, enforcement timetable, data-protection architecture and interoperability with Customs and tax systems. These will determine whether the portal becomes market infrastructure or merely another compliance website.
BRANDECONOMY Insight
Nigeria’s automotive market does need formalisation—but the objective must be economic enablement, not registration for registration’s sake.
The real test is not how many dealers upload documents. It is whether accredited businesses obtain cheaper financing, consumers suffer fewer fraudulent transactions, uncustomed vehicles disappear from formal showrooms and local assemblers gain fair access to government and commercial demand.
NADDC should publish measurable performance indicators: registration turnaround times, applicable fees, portal uptime, verified-dealer totals, financing facilitated, consumer complaints resolved and enforcement actions completed.
It should also establish an independent appeal process, provide a public verification tool and explain how dealership data will be protected and shared.
Done well, the registry could shift Nigeria’s motor trade from opacity towards accountable enterprise. Done badly, it would digitise bureaucracy while leaving the fundamental problems of finance, product integrity and consumer protection untouched.
The strategic opportunity is much larger than licensing. Nigeria can use dealer identity as the foundation for a connected automotive marketplace in which vehicles, sellers, lenders, insurers and regulators operate with greater visibility and trust.