
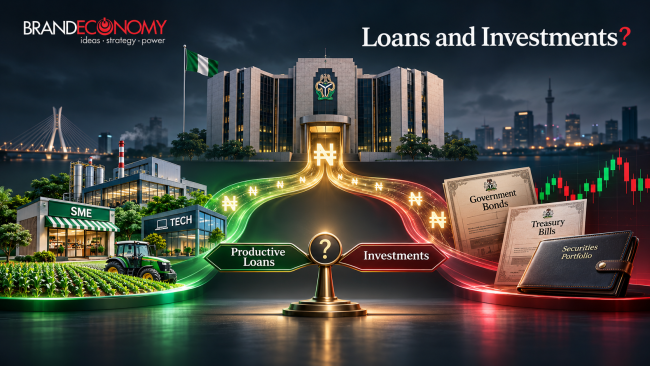
 A sharp reported decline in Nigerian banks’ use of the Central Bank of Nigeria’s standing facilities has strengthened expectations that lenders may be redeploying liquidity into loans and investments. But the data require more careful interpretation before the movement can be celebrated as a decisive return to productive-sector financing.
Reports based on the apex bank’s financial data said commercial banks’ placements through the Standing Deposit Facility fell by 87 per cent to ₦1.22 trillion in October 2026, from ₦9.4 trillion in September.
Banks’ borrowing through the Standing Lending Facility was also reported to have plunged by 98 per cent, from ₦920 billion in September to ₦15 billion in October.
Professor Uche Uwaleke, President of the Capital Market Academics of Nigeria, said the reduction could reflect banks’ deployment of more funds into credit, government securities and other financial-market investments instead of leaving surplus liquidity with the CBN.
His interpretation is plausible. It is not yet conclusive.
A reduction in money parked at the central bank may indicate that lenders have found more attractive uses for their funds. But it does not, on its own, reveal whether the money financed factories, small businesses and households—or migrated into Treasury bills, bonds, foreign-exchange transactions and other comparatively low-risk instruments.
What the two CBN facilities mean
The Standing Deposit Facility allows eligible financial institutions to place surplus funds with the CBN, usually overnight, and earn interest.
High SDF activity can indicate abundant banking-system liquidity. It can also suggest that banks lack sufficiently attractive lending opportunities or prefer the safety of a central-bank return to the risks associated with private borrowers.
The Standing Lending Facility operates in the opposite direction. It gives banks access to short-term CBN funding when they require liquidity to meet settlement or operational obligations.
A sharp fall in SLF borrowing could therefore indicate reduced overnight funding pressure, better liquidity distribution within the banking system or improved treasury management.
It does not necessarily mean that every bank is stronger. Aggregate figures can conceal differences between well-capitalised institutions with substantial liquidity and smaller banks confronting tighter funding conditions.
Uwaleke described the decline in SLF use as encouraging because it suggested that banks had less need for emergency or overnight support from the apex bank.
He attributed the wider movement to possible CBN liquidity absorption, changes in government cash flows, shifts in credit demand and adjustments to banks’ treasury strategies.
The interest-rate incentive changed
The monetary-policy environment provides an important part of the explanation.
Following the reduction of the Monetary Policy Rate to 23 per cent in September, the CBN placed its Standing Lending Facility rate at 23.5 per cent and its Standing Deposit Facility rate at 20 per cent.
That left the lending window 50 basis points above the policy rate and the deposit window 300 basis points below it. cbn.gov.ng
The lower SDF rate reduced the return available to banks for placing excess funds with the CBN. In principle, that should encourage lenders to search for higher-yielding opportunities elsewhere.
Those alternatives include private-sector loans, Treasury bills, Open Market Operation instruments, government bonds and interbank placements.
The policy transmission question is therefore not whether money left the SDF. It is where the money went next.
A material data question
The reported monthly figures also need methodological clarification.
While secondary reports put October SDF deposits at ₦1.22 trillion, the CBN’s published daily financial table showed net Standing Deposit Facility activity of about ₦7.19 trillion on October 30. The same official table recorded approximately ₦8.41 trillion on October 28 and ₦7.63 trillion on October 29.
The table showed no net SLF activity on October 30 and 29, but ₦15 billion on October 28. Central Bank of Nigeria
These figures may measure different things. One could represent an aggregation, average, adjusted monthly position or a particular reporting treatment, while the other captures daily closing activity.
Until the underlying methodology is stated clearly, the 87 per cent and 98 per cent comparisons should be treated as indicators requiring reconciliation—not self-explanatory proof of a structural shift.
This distinction matters because liquidity data can move dramatically within days as securities mature, government allocations enter the system and the CBN conducts auctions.
October was not simply a month of disappearing liquidity
Financial Markets Dealers Association data present a more complex picture.
The association reported that banking-system liquidity increased by 56.75 per cent to approximately ₦7.37 trillion in October, from ₦4.70 trillion in September.
The rise was supported by substantial OMO maturities, Treasury-bill repayments, government allocations and bond-coupon payments. Fresh OMO issuance did not fully absorb the money returned to investors.
Separate market analysis estimated that the CBN repaid about ₦10.69 trillion on matured securities during October—approximately ₦3.20 trillion more than it raised through new OMO and Treasury-bill auctions.
That suggests the financial system received a sizeable net injection during the month, even as banks altered their use of the standing facilities. punchng.com
The implication is that reduced facility use may reflect changing treasury behaviour within a still-liquid system rather than a straightforward reduction in surplus cash.
Has more money reached businesses?
There is some evidence that private-sector credit has expanded.
CBN figures cited in market reports showed credit to the private sector rising by about ₦3.96 trillion between April and August 2026, from ₦80.59 trillion to ₦84.55 trillion.
That expansion coincided with the banking recapitalisation programme, which increased the capacity of some institutions to grow their balance sheets.
However, the headline increase does not answer several critical questions:
- How much represented new lending rather than valuation effects or restructuring?
- Which sectors received the additional credit?
- What proportion went to large corporates compared with MSMEs?
- At what interest rates and repayment tenors?
- Did credit support new productive capacity or mainly working-capital survival?
- Were consumer and household borrowers included meaningfully?
High borrowing costs remain a major constraint. Even where banks possess liquidity, many businesses cannot profitably service commercial loans priced well above their operating margins.
The sovereign crowding-out problem
Government securities remain a formidable competitor for bank liquidity.
The International Monetary Fund reported that Nigerian banks’ holdings of government securities accounted for about 22 per cent of total assets, warning that high reserve requirements, structural constraints and sovereign borrowing could continue to crowd out private credit. imf.org
From a bank’s perspective, the attraction is understandable. Government instruments offer relatively strong yields, predictable cash flows and lower capital risk than lending to a manufacturer facing unstable electricity, currency exposure and weak consumer demand.
For the wider economy, however, persistent preference for sovereign assets can weaken financial intermediation. Nigerian Banks remain profitable, government borrowing is funded, but businesses struggle to obtain affordable capital.
A shift from the CBN deposit window into Treasury bills may improve bank returns. It does not necessarily expand Nigeria’s productive capacity.
Investor and market implications
For bank investors, reduced reliance on the SLF could be interpreted positively if it reflects stronger liquidity management and lower funding stress.
Declining SDF placements could also support interest income if banks redeploy funds into higher-yielding assets. But the quality of that income matters.
Aggressive loan growth can boost earnings while creating future non-performing loans. Heavy exposure to government securities can protect near-term asset quality while increasing the connection between banks and sovereign fiscal risk.
Investors should therefore examine each bank’s loan growth, sector concentration, cost of risk, deposit mix, liquidity ratio and government-securities exposure rather than relying on aggregate standing-facility data.
Brand implications for banks
For Nigerian banks, the issue is also reputational.
A bank cannot credibly present itself as an engine of enterprise if most deployable liquidity circulates between the central bank, government securities and a narrow group of blue-chip borrowers.
Businesses increasingly judge banking brands by access, speed, transparency and the real cost of credit—not by advertising claims about supporting entrepreneurs.
Lenders that convert recapitalisation into appropriately priced MSME, manufacturing, agricultural and technology financing will build stronger long-term trust than institutions that merely report larger balance sheets.
BRANDECONOMY Insight
The fall in banks’ reported use of CBN standing facilities is an important signal, but it is not yet evidence of a credit revolution.
Three tests will determine its economic significance.
First, the CBN should clarify the methodology behind the monthly SDF and SLF figures and reconcile them with its published daily positions.
Second, bank disclosures must show whether liquidity is moving into productive private-sector credit or mainly into government instruments.
Third, the quality of lending should be measured through additional output, employment, exports and business expansion—not simply nominal growth in loan books.
Nigeria does not merely need banks to move money away from the central bank. It needs them to move capital towards productive risk.
Until that happens at scale, lower SDF deposits may improve treasury efficiency without materially changing the financing reality confronting Nigerian businesses.