
 The Central Bank of Nigeria’s 307th Monetary Policy Committee meeting has given the market a new talking point, but it has not yet given the economy cheap money.
At its September 21–22, 2026 meeting, the MPC reset the Monetary Policy Rate at 23 per cent, recalibrated the standing facilities corridor to +50/-300 basis points around the MPR, and retained the Cash Reserve Requirement at 45 per cent for deposit money banks, 16 per cent for merchant banks and 75 per cent for non-TSA public sector deposits. On paper, the reduction in the policy rate sends a signal that the CBN is cautiously opening the door to a softer monetary cycle.
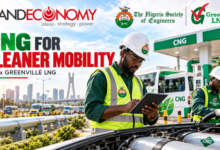
But Nigeria’s real economy does not live on policy signals alone. It lives on credit pricing, tenor, collateral demands, repayment flexibility, confidence, power supply, logistics costs, FX availability and the willingness of banks to take calculated risks on productive enterprise.
That is why MPC 307 should not be read merely as a rate story. It is a banking-sector character test.
The Banking Comfort Zone
For much of the recent tightening cycle, Nigerian banks have operated in a difficult but profitable environment. High interest rates raised funding costs for businesses and households, but they also created attractive opportunities for banks to earn strong returns from government securities and other relatively safer instruments.
This has produced an uncomfortable question: when risk-free or near-risk-free returns are attractive, why should a bank aggressively lend to manufacturers, farmers, exporters, logistics players, technology firms and SMEs battling power costs, weak consumer demand and foreign-exchange volatility?
That question is commercially rational. It is also developmentally dangerous.
A banking system can be profitable while the economy remains underfinanced. It can post strong earnings while SMEs are suffocating. It can satisfy shareholders in the short term while failing the broader enterprise base that should become tomorrow’s depositors, borrowers, employers and taxpayers.
This is the tension MPC 307 has brought back to the surface.
Lower MPR Does Not Automatically Mean Lower Lending Rates
The MPR reset matters because it affects market expectations and gives lenders, borrowers and investors a new reference point. However, commercial lending rates will not fall by magic.
Banks still face high CRR requirements, liquidity management constraints, credit-risk realities and the practical cost of doing business in Nigeria. With CRR for deposit money banks held at 45 per cent, a significant portion of bank deposits remains sterilised. That means the system is not yet being flooded with lendable liquidity.
For businesses, the more important question is not whether the policy rate has moved. It is whether actual borrowing costs will decline meaningfully, whether credit committees will become more flexible, and whether banks will be willing to extend longer-tenor facilities to businesses that create jobs and output.
The productive economy needs more than overdrafts. It needs working capital, equipment finance, trade finance, invoice discounting, export credit, agribusiness finance, clean-energy finance and structured SME lending that understands cash-flow cycles.
The Economy Is Growing, But Not Yet Transforming
Nigeria’s GDP growth has shown resilience, with recent data pointing to expansion in both oil and non-oil activity. But growth alone is not transformation. A country can grow statistically while factories remain underpowered, small businesses remain undercapitalised and households remain financially stressed.
That is why the credit question is central. Nigeria’s ambition cannot be built only on oil output recovery, public borrowing, remittances and financial-market activity. It requires credit moving into sectors that multiply value: manufacturing, agriculture, logistics, housing, digital infrastructure, export services, healthcare, education and renewable energy.
When credit is too expensive or too short-term, businesses postpone investment. When businesses postpone investment, productivity weakens. When productivity weakens, jobs suffer. When jobs suffer, household purchasing power declines. And when purchasing power declines, even banks eventually feel the weakness in deposits, loan demand and asset quality.
Productive credit is not charity. It is enlightened banking.
SMEs Are The Missing Middle
The biggest test of the post-MPC environment will be the SME segment. Nigerian banks often speak warmly about SMEs, but the lived experience of many small businesses is still defined by documentation barriers, collateral rigidity, high pricing and limited patience for business volatility.
Yet SMEs are exactly where inclusive growth is most likely to be unlocked. They employ, distribute, innovate and adapt faster than large bureaucratic systems. But they need financing products designed around reality, not textbook balance sheets.
A serious bank-led productive credit agenda would include sector-specific loan products, cash-flow-based lending, credit guarantees, digital transaction scoring, cluster financing and partnerships with fintechs, development finance institutions and state-level enterprise agencies.
The banks that master this space will not only earn income. They will earn trust.
Brand Implications For Nigerian Banks
This is where the issue becomes a brand-economy story. In a high-pressure economy, banking brands are no longer judged only by branch networks, mobile apps, corporate colours or award plaques. They are judged by usefulness.
Can your bank help a manufacturer survive a cost shock? Can it help an exporter bridge payment cycles? Can it support a woman-owned food processing business with equipment finance? Can it help a logistics firm convert fuel pressure into cleaner fleet investment? Can it finance solar adoption for SMEs struggling with diesel costs?
The next era of banking brand equity in Nigeria will be built around visible economic enablement.
Banks that continue to speak the language of empowerment while behaving as passive treasury machines will face a reputation gap. Banks that convert monetary easing into responsible credit expansion will own the stronger story: not just “we are profitable,” but “we are helping the economy work.”
That is a far more durable brand proposition.
Investor Relevance
For investors, MPC 307 presents both opportunity and caution.
A lower policy-rate environment could gradually compress some high-yield income lines, especially if the easing cycle continues. Banks that have leaned heavily on treasury income may need stronger loan growth, fee income, digital scale and sector expertise to sustain earnings momentum.
But aggressive lending in a fragile economy also carries asset-quality risk. The winners will be banks that can grow risk assets intelligently, not recklessly. Investors should therefore look beyond headline profits and interrogate loan-book composition, non-performing loan trends, cost of funds, capital adequacy, deposit mix, digital acquisition efficiency and exposure to vulnerable sectors.
The premium banking stocks of the next cycle may not simply be those with the largest balance sheets. They may be those with the best credit intelligence.
The Policy Challenge
The CBN has signalled cautious easing, but monetary policy cannot single-handedly produce productive credit. Fiscal policy, infrastructure delivery, security, tax administration, FX management and sector-specific reforms must align.
If power costs remain high, roads remain weak, insecurity disrupts farms and multiple taxation punishes enterprise, banks will remain cautious. No responsible lender can ignore operating risk. Therefore, government must understand that credit expansion is not merely a banking decision; it is also a function of the investment climate.
This is why MPC 307 should be treated as part of a wider national competitiveness conversation.
Nigeria does not only need cheaper money. It needs bankable businesses.
What BRANDECONOMY Will Watch
In the months ahead, the key indicators will be clear.
Will lending rates decline in a way borrowers can feel? Will banks increase credit to SMEs and productive sectors? Will manufacturers see improved access to working capital? Will fintech-bank partnerships deepen alternative credit scoring? Will development finance institutions provide more effective guarantees? Will banks publish stronger sectoral credit stories rather than generic CSR narratives?
Most importantly, will the CBN’s policy reset translate into measurable private-sector momentum?
That is the real story after MPC 307.
BRANDECONOMY Insight
CBN’s MPC 307 has changed the mood music, but not yet the dance. The reset to a 23 per cent MPR suggests that Nigeria may be entering a more accommodative phase, but the country’s growth challenge will not be solved by rate adjustment alone.
The deeper issue is whether Nigerian banking can move from profitable intermediation to productive intermediation.
For years, the economy has asked banks to do more than protect margins. It has asked them to finance enterprise, support resilience, back innovation and help convert national ambition into real output. The response has been mixed. Some banks have built strong sectoral playbooks. Others have remained more comfortable where risk is lower and yields are easier.
The next competitive frontier is clear: the most valuable Nigerian banks will be those that combine prudence with productive courage.
They will not lend blindly. But they will understand sectors deeply. They will use data better. They will partner more intelligently. They will create products that match business cycles. They will treat SMEs not as charity cases but as tomorrow’s corporate clients.
MPC 307 is therefore not just a CBN story. It is a mirror held up to Nigerian banking.
The banks that read it correctly will help build the next economy. The banks that miss it may still make money, but they will lose something more strategic: relevance.