Cardoso Puts MPC Independence at the Heart of CBN Credibility Reset

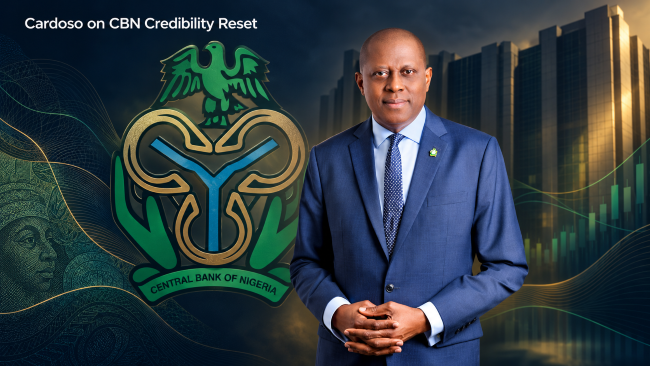
CBN Governor Yemi Cardoso says rigorous debate, independent external members, and clearer communication now underpin monetary policy. For markets, however, credibility will be measured by observable conduct—not institutional assurances.
Central Bank of Nigeria Governor Olayemi Cardoso has placed the independence and intellectual diversity of the Monetary Policy Committee at the centre of his campaign to rebuild confidence in Nigeria’s monetary authority.
Speaking on Thursday at the IMF and World Bank Group Annual Meetings in Bangkok, Thailand, Cardoso said the CBN was building an MPC whose decisions would be grounded in rigorous analysis, open debate and the freedom of members to challenge prevailing assumptions.
His intervention came during a high-level session titled, “How Central Banks Decide—Committee Decision-Making and Communication in an Era of Uncertainty,” alongside Emmanuel Moulin, Governor of the Banque de France, and Martin Schlegel, Chairman of the Governing Board of the Swiss National Bank. The discussion was moderated by IMF First Deputy Managing Director Dan Katz.
For Nigeria, the conversation was more than an academic examination of central banking practice. It touched the credibility deficit the CBN inherited after years in which monetary policy, development intervention, deficit financing and foreign-exchange management frequently became entangled.
Cardoso acknowledged that his leadership assumed office during a period of crisis. Restoring confidence, he argued, required more than changing interest rates or reforming the foreign-exchange market. It required rebuilding the institutional machinery through which policy decisions are made.
External members as a defence against groupthink
A central element of that effort, according to Cardoso, has been the appointment of recognised and independent-minded external members to the MPC.
Internal members possess substantial institutional knowledge and have regular access to the CBN’s operational data. But that familiarity can create the risk of groupthink—particularly where officials examine the same information through similar institutional lenses.
External members are expected to introduce alternative interpretations, interrogate established assumptions and prevent policy consensus from becoming automatic compliance.
Cardoso said committee members receive economic data ahead of meetings, giving them time to conduct independent analysis, test scenarios and seek clarification from the MPC secretariat. External members may also consult specialists outside the CBN when additional expertise is required.
The Bank organises retreats and technical engagements outside the formal meeting cycle, sometimes involving experts from other central banks. Importantly, Cardoso said external members were brought into Nigeria’s transition towards an inflation-targeting framework from an early stage, rather than invited merely to endorse decisions developed elsewhere.
He also rejected the suggestion that his position as governor allowed him to predetermine outcomes with internal members. According to him, there are no preliminary meetings at which a preferred decision is privately agreed before the full committee convenes.
That assurance is important. But central-bank independence cannot depend only on the personal restraint of the governor. The stronger test is whether the institution possesses durable safeguards that can survive changes in leadership.
Independence must be visible
Nigeria’s MPC is designed under the CBN Act as a 12-member body comprising the governor, four deputy governors, two members of the Bank’s board and five external members—three appointed by the President and two by the governor.
At the time of writing, however, the CBN’s publicly available committee page displayed 11 names. This could reflect a vacancy or a delay in updating the webpage, but a central bank making transparency central to its credibility proposition should clarify the discrepancy.
More fundamentally, “independent-minded” appointments are not automatically the same as institutional independence. Markets will look for evidence that members can dissent without penalty, receive information on equal terms, disclose potential conflicts and publish their reasoning promptly.
The publication of individual MPC statements is therefore particularly valuable. Dissent should not be treated as institutional weakness. In credible monetary systems, reasoned disagreement helps investors understand the range of risks being considered and whether consensus was earned through analysis or produced through hierarchy.
The credibility test after the surprise rate reset
Cardoso’s comments are especially relevant following the MPC’s decision on September 22 to reset the Monetary Policy Rate from 26.5 per cent to 23 per cent—a substantial 350-basis-point adjustment that surprised many market participants.
The committee also recalibrated the standing-facilities corridor to 50 basis points above and 300 basis points below the policy rate. However, it retained the Cash Reserve Requirement at 45 per cent for deposit money banks, 16 per cent for merchant banks and 75 per cent for non-Treasury Single Account public-sector deposits.
The decision was taken against a more supportive macroeconomic background. Headline inflation had eased to 15.39 per cent in August, while gross external reserves stood at $55.25 billion on September 18, their highest level in about 18 years. Economic growth had also remained positive.
Cardoso conceded that markets generally dislike surprises but maintained that the CBN devoted more time than usual to explaining the context behind the decision. Investors, he suggested, eventually understood that the adjustment was intended partly to correct weaknesses in monetary-policy transmission.
That defence is plausible, but it also exposes the next challenge. Effective communication is not merely the ability to explain a decision after it has shocked the market. It is the ability to establish a sufficiently intelligible policy framework that investors understand the central bank’s reaction function before the announcement.
A surprise can be justified. Persistent surprise is a credibility problem.
Coordination without subordination
Cardoso also highlighted improved coordination between fiscal and monetary authorities, including an agreement intended to strengthen cooperation between both sides.
Better coordination can prevent government spending, debt issuance and banking-system liquidity from undermining monetary policy. It can also help the CBN manage inflation without repeatedly imposing excessive tightening on businesses and households.
Yet coordination must not become subordination. A central bank cannot credibly target inflation if fiscal demands determine its liquidity operations, exchange-rate stance or financing decisions.
The principle should therefore be clear: fiscal and monetary authorities may coordinate information, timing and economic objectives, but responsibility for price stability must remain operationally protected.
What the policy shift means for banks and businesses
For banks, the lower policy rate could support bond valuations and gradually reduce wholesale funding costs. It may also create room for lending rates to moderate if liquidity conditions permit.
But the continuing 45 per cent reserve requirement means the reduction in the headline policy rate will not automatically produce cheaper or more abundant private-sector credit. A substantial portion of bank deposits remains sterilised, while liquidity operations and credit-risk pricing continue to shape the rates offered to businesses.
Banks with large fixed-income portfolios may benefit from declining yields, although a sustained easing cycle could place pressure on interest margins. Institutions with disciplined credit underwriting and strong transaction-banking franchises may be better positioned than those excessively dependent on high-yield government securities.
For manufacturers, small businesses and consumers, the decisive question is whether the reset reaches the real economy. A lower MPR that does not reduce borrowing costs, improve loan availability or stimulate productive investment will amount to a financial-market adjustment rather than a development breakthrough.
Monetary policy also cannot, on its own, resolve the structural drivers of Nigerian inflation. Food insecurity, unreliable electricity, transport bottlenecks, exchange-rate exposure and weak agricultural productivity require coordinated supply-side intervention.
Brand and investor implications
A central bank is ultimately a trust brand. Its product is confidence: confidence in the currency, in the integrity of its data, in the consistency of its rules and in the ability of its leadership to resist political or short-term commercial pressure.
For international investors, the most valuable monetary authority is not necessarily the most aggressive or accommodating. It is the one whose policy framework is coherent, whose information is credible and whose actions can be understood within a stable institutional logic.
Cardoso’s emphasis on independent deliberation therefore has direct implications for Nigeria’s sovereign-risk premium, exchange-rate expectations, government borrowing costs and ability to retain long-term capital.
Investors will nevertheless expect more than reassuring presentations at international meetings. They will monitor whether individual MPC statements are released promptly, whether divergent votes are clearly recorded, whether overnight rates remain aligned with the policy corridor and whether reserve disclosures distinguish gross buffers from immediately available external liquidity.
BRANDECONOMY Insight
Cardoso has correctly identified the committee room as one of the most important theatres in the battle to restore the CBN’s credibility. Monetary-policy legitimacy begins with the quality of the argument before it becomes the authority of the decision.
But independence is not something an institution can establish solely by declaring it. It must be observable in appointments, disclosures, voting records, dissent, data access and the willingness to resist both fiscal pressure and market fashion.
The September rate reset may ultimately prove well judged. Inflation had moderated, reserves had strengthened and the existing policy rate no longer appeared fully aligned with market conditions. Still, a central bank that surprises investors and then relies on post-meeting explanation has more work to do on forward guidance.
The strongest evidence of Cardoso’s promised credibility reset will arrive when markets can understand the CBN’s likely response to changing economic conditions before the governor explains it—and still trust the institution when its final decision differs from expectations.