NIBSS Bets on Open-Source jPOS to Power Nigeria’s Payments Future

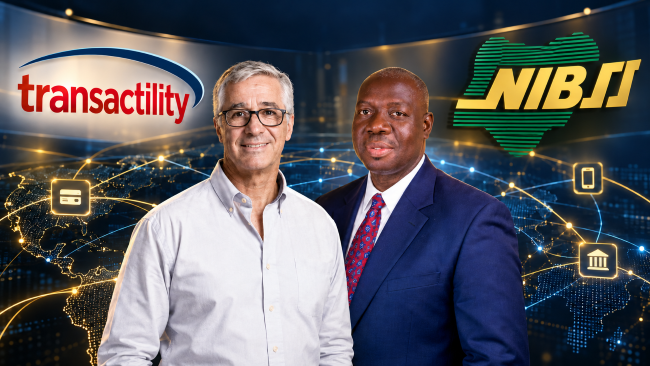 The Nigeria Inter-Bank Settlement System has selected technology from Transactility Inc.’s jPOS ecosystem to support the National Payment Stack, deepening Nigeria’s shift towards a more flexible, interoperable and locally controlled payments architecture.
NIBSS disclosed on Tuesday that the National Payment Stack, its next-generation instant-payment infrastructure, incorporates Transactility’s jPTS transaction switch, built on the open-source jPOS framework.
The decision is not the launch of an entirely new platform. Rather, it provides greater clarity on the technology underpinning an NPS rollout that has already begun processing transactions across banks and other participating institutions.
NIBSS said it had used jPOS technology for several years, particularly in processing payment messages based on ISO 8583—the longstanding standard commonly associated with card and electronic transaction systems.
The National Payment Stack introduces support for ISO 20022, a richer global messaging standard that allows payment instructions to carry more structured information. That expanded data capability can improve reconciliation, regulatory reporting, fraud monitoring and cross-border interoperability.
From Processing Transactions to Managing Payment Intelligence
NPS is designed to support account-to-account instant transfers, merchant payments through QR codes, bulk payments and alias-based addressing that can allow customers to receive money using identifiers such as telephone numbers.
The architecture combines internally developed NIBSS capabilities with open-source and enterprise technologies. Significantly, the arrangement gives NIBSS access to the underlying source code, enabling its engineers to customise the platform and determine its development priorities.
Premier Oiwoh, Managing Director and Chief Executive Officer of NIBSS, said the system had been developed for the scale and particular demands of Nigeria’s payment market. He added that the jPOS ecosystem would give NIBSS the flexibility to continue improving the platform as market requirements change.
That flexibility matters. National payment systems are too economically important to depend entirely on the timetable, licensing structure or strategic priorities of a single proprietary software provider. Control over the codebase can reduce vendor lock-in, shorten product-development cycles and enable faster responses to new regulations, fraud patterns and consumer behaviour.
However, access to source code should not be mistaken for automatic technological sovereignty. Genuine control requires experienced engineers, disciplined software governance, continuous security testing and robust arrangements for disaster recovery and operational resilience.
Market Implications
For commercial banks, fintech companies and payment-service providers, a modular NPS could lower integration barriers and accelerate the introduction of new services. Richer payment data could also improve automated reconciliation, reduce operational disputes and support more precise risk management.
Merchants may benefit from more reliable account-to-account and QR payments, while phone-number addressing could simplify transactions for consumers who struggle to remember or correctly enter bank-account details.
Government institutions could use the infrastructure to improve tax collections, social-benefit payments and bulk disbursements. The larger prize is the creation of a unified transaction layer connecting banks, fintechs, public institutions, businesses and consumers.
NPS had already crossed 100 million processed transactions by late September 2026, indicating that the platform is moving beyond concept stage. The more consequential test will be whether that transaction growth produces fewer failed transfers, faster dispute resolution and lower costs for consumers and businesses.
Brand and Investor Relevance
Payments infrastructure operates largely out of public view until it fails. For NIBSS, the adoption of an open, adaptable architecture strengthens its positioning as a builder of national digital infrastructure rather than merely an interbank processor.
Yet the NIBSS brand will ultimately be judged by outcomes: availability during peak periods, resistance to cyberattacks, transaction traceability and the speed with which unsuccessful payments are reversed.
For investors, the architecture could expand opportunities in fraud analytics, cybersecurity, identity services, merchant acquiring, payment orchestration and cross-border settlement. It may also help Nigerian fintechs build products on a common foundation instead of repeatedly constructing fragmented connections to multiple institutions.
Alejandro Revilla, founder and Chief Technology Officer of Transactility, described the selection as a milestone for both the company and the wider payments community. He said NPS demonstrated how open technology, combined with local engineering, could support national-scale infrastructure.
Transactility, headquartered in Boca Raton, Florida, is the commercial steward of jPOS and provides transaction-switching, card-management and messaging products to clients across more than 120 countries.
BRANDECONOMY Insight
NIBSS is making an important architectural bet: that open technology plus Nigerian engineering can deliver greater agility than dependence on an inflexible proprietary payment stack.
The opportunity is considerable, but so is the burden of proof. Open-source infrastructure must still be secured, audited, maintained and governed to national-system standards. NIBSS should therefore publish transparent performance indicators covering uptime, transaction failure rates, reversals, fraud detection and dispute resolution.
Nigeria does not merely need a faster payments platform. It needs trusted digital infrastructure that remains dependable when transaction volumes surge, fraudsters adapt and millions of consumers simultaneously expect their money to arrive.